Real estate underwriting, from first look to final offer
How investors turn a property’s documents into a decision: verifying income and expenses, modeling debt, computing the return metrics that matter, stress-testing the assumptions, and arriving at a price they can defend.
Written for investors underwriting their own deals — first analysis or five-hundredth — and for anyone who wants to understand what the numbers in an investment summary actually mean.
Real estate underwriting is the process of analyzing a property’s income, expenses, financing and risks to decide what it is worth to you and whether to buy it. It replaces the seller’s story about the property with your own evidence-based model: what the property actually earns today, what it will cost to own, what the debt requires, and what has to go right for the projected return to arrive.
The word comes from lending — a bank underwrites a loan by deciding whether the collateral and the borrower support it — but investors underwrite for a different question: not “will this loan be repaid” but “is this deal worth doing at this price.” The mechanics overlap; the standard of evidence should not be lower on the buy side than it is at the bank.
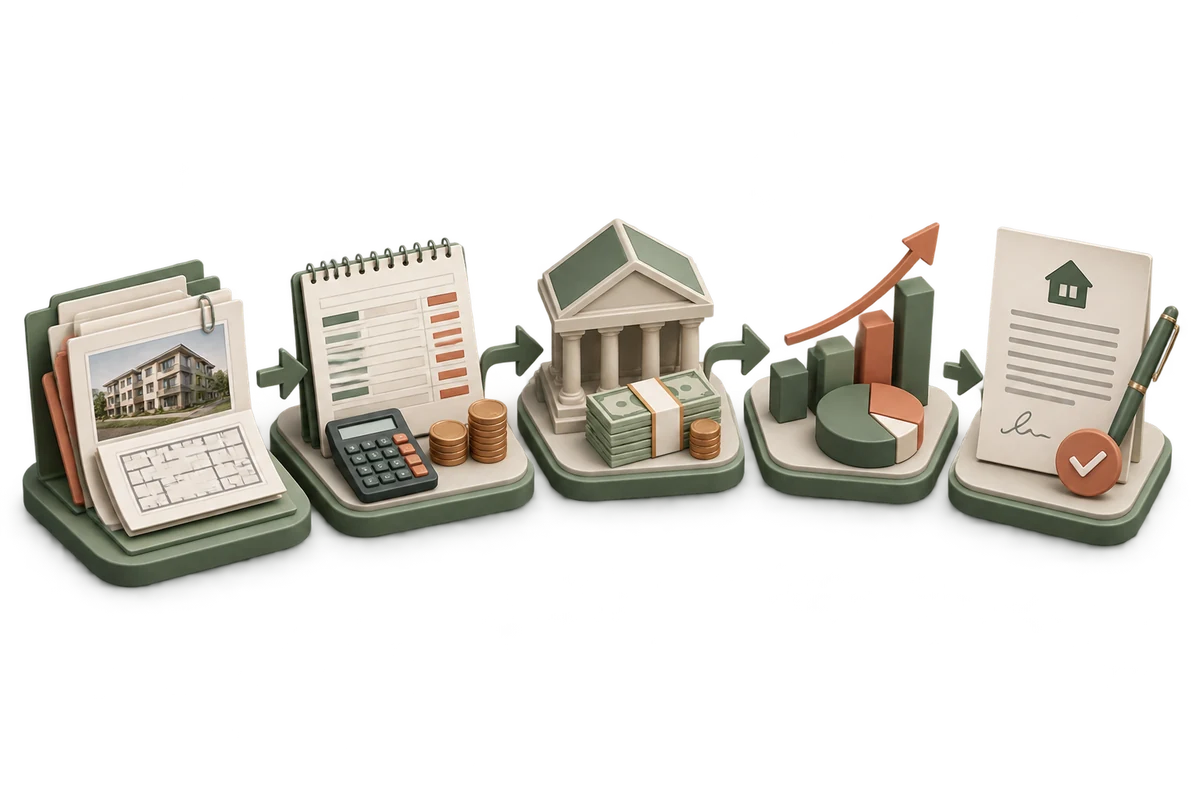
The process, in order
Underwriting runs in a sequence, and the order matters because each step feeds the next: establish the property’s current income from documents, not the listing; establish real operating expenses, including the ones the seller does not pay but you will; subtract to get net operating income; layer on the financing to get debt service and cash flow; project the hold through to an exit; and only then compute returns and back into the price that earns them. Investors who start from the asking price and work backward to justify it are not underwriting — they are negotiating with themselves.
Go deeper: Commercial Real Estate Underwriting 101: A Beginner’s Guide to Deal Evaluation · The Ultimate Guide to Commercial Real Estate Underwriting · How to Evaluate a Commercial Real Estate Deal in Under 10 Minutes
Operating assumptions: evidence before optimism
Every underwriting model is a stack of assumptions, and the discipline is sourcing each one. In-place income comes from leases and collections, not from “market rent.” Expenses come from actual statements, adjusted for what changes at sale — property taxes often reset on the purchase price, insurance gets re-quoted, and management costs what your manager charges, not what the owner-operator paid themselves.
Vacancy is a market fact you look up, not a plug. The gap between the seller’s pro forma and your evidence-based model is normal; it is also exactly where deals are won and lost.
Go deeper: The Importance of Using Financial Data in Your Underwriting
Financing assumptions shape everything downstream
Debt determines cash flow, and the lender’s constraints often determine price. The loan is sized by loan-to-value and by coverage — the debt service coverage ratio, the property’s NOI against its annual debt payments — and whichever binds first sets the proceeds.
Rate, amortization and any interest-only period change the annual payment, and therefore every levered return in the model. Benchmark rates move these assumptions between the day you underwrite and the day you close, which is a reason to stress the rate, not to guess it precisely.
Go deeper: What Is DSCR and Why Is It Useful in Real Estate Investing? · The Role of SOFR Rates and Treasury Rates in Real Estate Underwriting
The return metrics, and what each one is for
No single number describes a deal. Cap rate prices the property independent of financing; cash-on-cash measures what your invested cash earns each year; IRR weighs every cash flow by when it arrives; equity multiple says how many dollars come back per dollar in, ignoring time; DSCR and debt yield are the lender’s view of the same property.
Each answers a different question, and the common mistake is optimizing one — usually IRR — while ignoring what the others are saying about risk.
Go deeper: How to Calculate Net Operating Income (NOI) for Real Estate? · How to Calculate Cash Flow in Real Estate? · How to Calculate Return on Investment (ROI) in Real Estate
Scenarios, sensitivity and the exit
A single projection is a guess; underwriting is testing the guess. Scenario analysis re-runs the same deal under different assumption sets — a softer exit cap rate, slower rent growth, a higher rate at refinance — and shows which assumptions the deal can survive and which it cannot.
The exit deserves particular suspicion, because a distant sale price at an assumed cap rate carries more of the projected return than any near-term number, and it is the assumption you have the least evidence for.
Go deeper: How to Use Multiple Scenarios in Your Next Real Estate Deal?
Where underwriting goes wrong
Most underwriting failures are not math errors; they are accepted inputs. Trusting the seller’s pro forma expenses, growing rents faster than the market’s own record, compressing the exit cap rate below today’s, skipping the tax reassessment, sizing reserves at zero — each produces a model that is internally consistent and wrong.
The red-flag and mistake guides below catalogue the recurring ones, with the control for each.
Go deeper: 5 Red Flags to Consider in Real Estate Underwriting · The 7 Biggest Mistakes Real Estate Investors Make
From the model to the offer
The model’s job is a number you can act on: the price at which the deal clears your return target and the lender’s constraints. From there the work is transactional — a letter of intent, negotiation, and due diligence that verifies in the field what the documents claimed on paper.
Due diligence is not a repeat of underwriting; it is the audit of it.
Go deeper: 5 Questions to Ask Before Buying an Investment Property · Letter of Intent (LOI): The Quick Guide to LOIs in Real Estate · How to Master Due Diligence in Real Estate in 8 Steps
The metrics, briefly
Short versions here; where a full article exists, it owns the detailed treatment.
Net operating income (NOI)
All operating income minus all operating expenses, before debt service and capital costs. The number nearly every other metric is built on.
Read the full article →Cap rate
NOI divided by price. What the property yields with no financing — and, inverted, how the market converts income into value.
Read the full article →DSCR
NOI divided by annual debt service. Below 1.0× the property does not cover its own loan; lenders size loans to keep it comfortably above.
Read the full article →Cash flow
What is left after operating expenses and debt service. The rent check’s honest remainder, and the number that pays you during the hold.
Read the full article →Cash-on-cash return
Annual pre-tax cash flow divided by the cash actually invested. It moves when the financing moves; cap rate does not.
IRR
The discount rate at which the deal’s cash flows — in and out, timed — net to zero. Rewards money returned early; the metric most sensitive to the exit assumption.
Equity multiple
Total cash returned divided by total cash invested. Blind to time — a 2.0× over four years and over twelve years read the same — which is why it is paired with IRR.
Debt yield
NOI divided by the loan amount. The lender’s cushion expressed without rate or amortization, so it cannot be flattered by loan structure.
ROI
Gain divided by cost, in its simplest form. Useful shorthand; too coarse to underwrite with on its own, which is what the levered and time-weighted metrics above are for.
Read the full article →Go deeper, by subtopic
The underwriting process5 articles
- Commercial Real Estate Underwriting 101: A Beginner’s Guide to Deal Evaluation
- The Ultimate Guide to Commercial Real Estate Underwriting
- How to Evaluate a Commercial Real Estate Deal in Under 10 Minutes
- How to Invest in Real Estate: A Beginner’s Guide
- The Importance of Using Financial Data in Your Underwriting
The metrics6 articles
- How to Calculate Net Operating Income (NOI) for Real Estate?
- What Is DSCR and Why Is It Useful in Real Estate Investing?
- What Is a Good Cap Rate for Multifamily Investment?
- How to Calculate Cash Flow in Real Estate?
- How to Calculate Return on Investment (ROI) in Real Estate
- Why Having Equity Is Important for Investors in 2024?
Assumptions, scenarios and rates2 articles
Mistakes and red flags3 articles
From analysis to offer4 articles
Related guides: Multifamily Investing · Real Estate Development · Self-Storage Investing · Single-Family Investing · All guides
 Put it into practice
How DealWorthIt fits in
Turn the principles in this guide into an investment case you can review and share.
- 01
Build the model
Connect income, expenses, financing, and exit assumptions in an asset-specific workflow.
- 02
Test the assumptions
Save alternative scenarios to explore a different price, rate, or operating plan.
- 03
Share the analysis
Create a shared report webpage or download a PDF from the analysis.
Document import, advanced projections, and side-by-side scenario comparison require Gold or Diamond.
Build the rental income
- Units
- —
- Monthly rent / unit
- —
- Scheduled annual rent
- —
- Vacancy allowance · 5%
- —
12 units × $1,600 × 12 months, less 5% vacancy.
Animated demo · Illustrative assumptions · Projections are not guaranteed
Underwrite your next deal with the assumptions visible
Run the numbers on a real property — income, expenses, debt, scenarios and returns — and share the result as an investor-ready report.