Real estate syndication software

Real estate syndication software that models the deal and the waterfall together

Underwrite the property, set the equity structure, and see how projected cash flow and sale proceeds reach LPs and the GP. Keep preferred returns, residual splits, and investor economics beside the deal.

Explore the LP / GP splitInteractive sample
DealWorthItIllustrative allocation
LP / GP ECONOMICS

Follow the distribution

$1,000,000 LP equity · No sponsor co-invest

$120,000
  1. 01
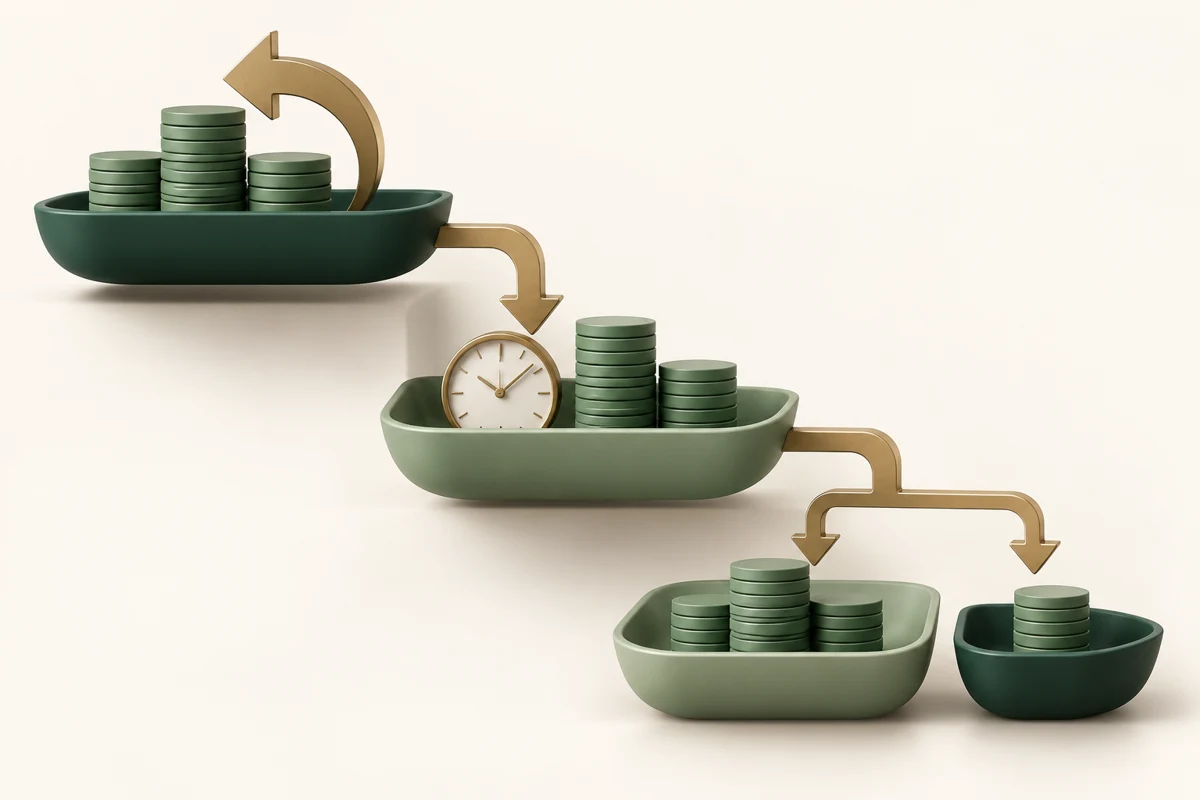
    Return capitalCapital stays invested during operations
    $0
  2. 02
    Pay the preferred return$80,000 due for one year
    $80,000
  3. 03
    Split the residualLP $28,000 · GP $12,000
    $40,000
Total to LPs$108,000
Total to GP$12,000

Simplified single-year example with no prior accrued preferred, fees, taxes, or GP co-invest. The full model carries unpaid preferred across years. No GP catch-up or multi-tier IRR hurdles. Syndication modeling requires Gold or Diamond.

Investment partners reviewing a property analysis
The deal and its investors

Connect property performance to investor economics.

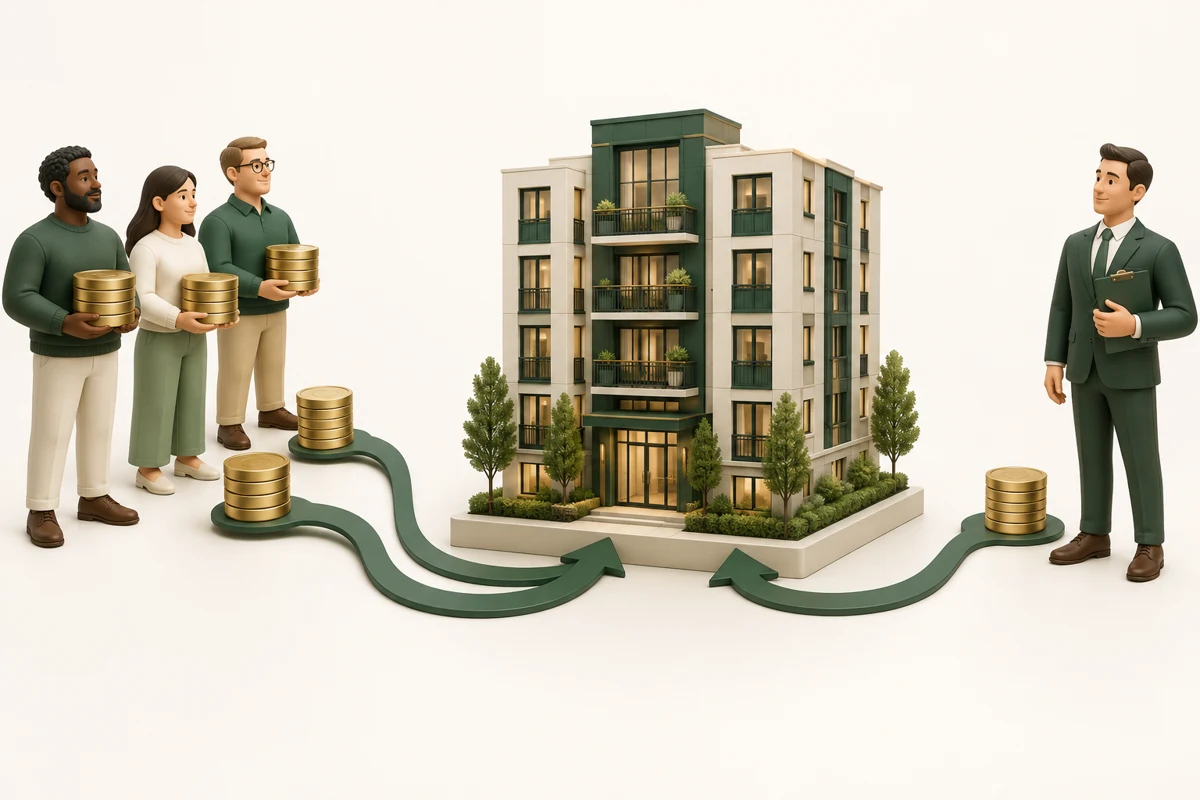
A real estate syndication pools capital from multiple investors to acquire or operate a property. The general partner (GP) manages the investment and may invest its own capital.

Limited partners (LPs) contribute equity and receive distributions under the agreed terms.

DealWorthIt shows how projected cash flow and sale proceeds would be shared under the terms you enter. Change a property assumption or an equity split to see how investor results change.

It does not manage investors, raise capital or move money.

The two sides

Who invests, who manages, and who receives what

The GP — the sponsor

The sponsor manages the investment and may contribute capital. Define its role and compensation in the model:

  • Manager groups, such as GP and co-GP, share the manager pool
  • GP co-invest: the dollars the sponsor contributes
  • Promote: the GP share of remaining profits after the preferred return
  • Sponsor fees, modeled separately from the promote

Co-invest and promote terms vary by deal. Enter your agreed terms rather than assuming a standard split.

The LPs — passive investors

Passive investors contribute equity. Define the terms for each LP group:

  • LP member groups, each with its share of the member equity pool
  • A preferred return rate per group
  • A preferred-return-only option for members who take the pref without a residual share
  • Allocation checks ensure each side totals exactly 100%

Legal arrangements vary; the model describes economics, not the legal documents that create them.

A waterfall cannot rescue weak property economics. Everything a syndication distributes comes from the underlying deal: the purchase, the income and expenses, the financing, the hold-period cash flow, and the refinance and sale assumptions.

The syndication model allocates projected returns; it does not create them.

That is why DealWorthIt models the syndication inside the deal analysis rather than in a separate waterfall spreadsheet. The equity structure sits on top of the same multifamily underwrite — the same NOI, the same debt, the same exit — so when an assumption moves, the LP and GP economics move with it instead of waiting for someone to re-key a second model.

The T12 and rent roll establish the operating model. The syndication structure determines how the resulting projected economics are shared.

Explore the property analysis: multifamily underwriting · T12 & rent roll analysis · real estate underwriting software

The workflow

Underwrite, structure, allocate, compare, report

The syndication is a layer of the deal analysis, not a separate product — each stage below runs in the same workspace as the underwrite.

Silver includes 3 scenarios per deal, Gold 10, Diamond unlimited; side-by-side comparison is a Gold and Diamond feature.
Plan details and feature availability live on the pricing page.

The structure

Start with who contributes the equity

Start with the equity required to fund the purchase, costs, and planned improvements. Allocate it between LP investors and GP co-invest. See what remains to be funded as you build the structure.

The waterfall

How cash moves through the waterfall

Follow the cash in order: return capital at a refinance or sale, pay the cumulative preferred return, then divide the remaining cash using one LP/GP split.

A preferred return is not a guaranteed return

A preferred return is a distribution priority: one class of investors stands first in line for distributions up to a stated rate before later profit-sharing applies. It is not a promise that the deal earns enough cash to pay it.

If projected cash flow falls short, the model shows the unpaid preferred accruing as a deficiency — it does not invent the money. Modeled distributions are projections, not actual investor payments or guaranteed returns.

Sponsor fees

Sponsor fees, kept apart from the promote

A promote is not the same as an acquisition or management fee. The promote is a share of profits above the preferred return; fees are compensation for work, and DealWorthIt models the two separately so neither hides inside the other.

Worked example

A worked example: one structure, two years and an exit

Follow a fictional deal, Sample Apartments, through two operating years and a sale. Every figure below is invented for the illustration. All terms are example-only.

The example structure

TermExample only
Total equity$4,000,000
LP member group$4,000,000 · 100%
Sponsor / GP co-invest$0 (optional — kept at zero here so the preferred-return math stays plain)
Preferred return8% · cumulative, simple accrual
Residual split70% LP / 30% GP

Two operating years

  • Year 1 — distributable cash $280,000. The pref accrues 8% × $4,000,000 = $320,000; the cash covers $280,000 of it, and the unpaid $40,000 carries forward. Residual: $0.
  • Year 2 — distributable cash $400,000. The carried $40,000 is paid first, then the current $320,000 pref: $40,000 + $320,000 = $360,000. The remaining $400,000 − $360,000 = $40,000 splits 70/30 — LP $28,000, GP $12,000. LP receives $388,000 in total.

At the sale

  • Sale proceeds to equity: $6,000,000, with the preferred paid current.
  • Return of capital first: $4,000,000 back to the LP group.
  • The remaining $6,000,000 − $4,000,000 = $2,000,000 splits 70/30 — LP $1,400,000, GP $600,000.

That is the mechanism; the model runs it every projection year across the full hold and reads the results out as LP IRR, equity multiples and a year-by-year distribution schedule. All terms above are example-only — preferred rates, splits and structures are negotiated per deal.

The outputs

The investor-level outputs

These are modeled outputs computed from your assumptions — projections of the structure you entered, not records of anything paid.

  • LP IRR — a full cash-flow IRR on the LP side
  • GP annualized return — an approximation from GP cash and capital, deliberately labeled as an annualized return rather than an IRR
  • LP and GP equity multiples
  • Capital invested, return of capital, preferred and residual distributions, and total cash returned — per side
  • Preferred paid each year, and any unpaid preferred carried forward
  • A year-by-year LP/GP distribution schedule with charts, and project-level IRR and equity multiple alongside

When a scenario cannot produce a full projection set, the investor tables say so rather than rendering zeros — a displayed $0 return is a financial claim, and the model refuses to make it by accident.

The metrics themselves, in the guides: NOI · DSCR · the full underwriting guide

Scope of the software

Know what the model covers

Use DealWorthIt for deal economics. Keep investor operations and professional advice in their own workflows.

The alternative

The waterfall, without the spreadsheet plumbing

Excel remains flexible and powerful for custom waterfalls. DealWorthIt connects a defined three-step waterfall to your property model. Sophisticated or highly bespoke waterfalls may still require custom modeling.

The spreadsheet workflow

  • Underwrite the property in one model, the waterfall in another
  • Build the pref accrual and deficiency logic by hand, per deal
  • Re-wire the formulas every time the structure changes
  • Copy updated cash flows across whenever the underwrite moves
  • Duplicate tabs for every structure you want to test
  • Rebuild the investor summary for every audience

The connected workflow

  • One deal model — the waterfall reads the underwrite directly
  • Cumulative preferred with carried deficiency, built in
  • Structured inputs: member groups, co-invest, pref, promote, fees
  • Assumption changes flow straight through to LP/GP economics
  • Saved scenarios compared side by side
  • A report with a dedicated syndication section, generated from the analysis
Fit

Who it’s for — and what it isn’t

Built for

  • Multifamily and self-storage syndicators structuring LP equity
  • Sponsors testing how a pref and promote shape their own economics
  • Acquisition teams underwriting deals that will be syndicated
  • Operators presenting projected LP economics alongside the underwrite
  • LPs who want to model what a sponsor’s structure implies before committing capital

Not a replacement for

  • Investor CRM, investor-portal or fundraising software
  • Fund administration, transfer-agent or capital-call management
  • Payment or distribution processing of any kind
  • K-1 preparation, tax reporting or accounting software
  • PPM, subscription-agreement or legal-document drafting
  • A substitute for legal, tax or securities advice

DealWorthIt is decision-support software. It models projected deal and syndication economics from the assumptions entered; it does not provide investment, legal, tax or securities advice, and modeled results should be reviewed and validated before making investment decisions.

Questions

Real estate syndication software, answered

What is real estate syndication software?

Real estate syndication software models how a deal’s projected returns are shared between the sponsor (GP) and passive investors (LPs). In DealWorthIt that means defining the equity structure — LP member groups, sponsor co-invest, a preferred return and a promote split — on top of the property underwrite, and reading out the projected LP and GP economics year by year.

It is modeling software, not investor-relations software: it does not manage investors, raise capital or move money.

What is a real estate syndication?

A real estate syndication pools capital from multiple investors to acquire or operate a property. The sponsor or GP typically manages the deal and may contribute capital; passive investors or LPs typically contribute most of the equity and participate in distributions under the agreed economic structure.

The specifics — splits, preferences, fees — are negotiated per deal.

What is a preferred return?

A preferred return is a distribution priority: a stated rate one class of investors accrues, and stands first in line for, before later profit-sharing tiers apply. In DealWorthIt the preferred return is set per LP member group, accrues annually on unreturned capital, and is cumulative — unpaid amounts carry forward and are paid first out of future cash.

Accrual can be simple or compounding, per deal.

Is a preferred return guaranteed?

No. A preferred return defines who gets paid first, not whether there is enough cash to pay them.

If the deal underperforms its projections, the preferred can go unpaid — DealWorthIt models that as an accruing deficiency rather than assuming the cash exists. No modeled distribution is a guaranteed return.

What is a real estate equity waterfall?

An equity waterfall is the ordered set of rules a deal uses to allocate distributable cash between investor classes. DealWorthIt models a three-step waterfall: return of capital at a refinance or sale, then the cumulative preferred return, then a single residual LP/GP split — the promote.

It does not model IRR-hurdle tier ladders or a separate GP catch-up tier.

What is a GP promote?

A promote — sometimes called carried interest — is the sponsor’s share of profits above the preferred return, larger than its share of contributed capital. In DealWorthIt the promote is the GP percentage of the residual split, and it is kept strictly separate from sponsor fees and from any capital the GP co-invests.

Can DealWorthIt model LP and GP returns?

Yes. The model computes LP IRR as a full cash-flow IRR, LP and GP equity multiples, per-side capital invested, return of capital, preferred and residual distributions, total cash returned, and a year-by-year distribution schedule.

The GP figure is an approximate annualized return rather than a cash-flow IRR, and the model labels it that way.

Does DealWorthIt support multiple waterfall tiers?

It supports one defined structure: return of capital, then the preferred return, then a single residual promote split. It does not support arbitrary or unlimited tiers, IRR or equity-multiple hurdles, or a GP catch-up tier — the model reports catch-up as not modeled.

Deals with waterfalls outside that structure may need custom modeling.

Does DealWorthIt manage investors or send distributions?

No. DealWorthIt is not an investor CRM, portal, transfer agent or fund administrator, and it does not process payments, execute distributions, manage capital calls or hold funds.

Its distributions are modeled projections of the structure you enter, not transactions.

Does DealWorthIt generate K-1s, PPMs or other legal documents?

No. It does not prepare K-1s or tax documents, and it does not draft PPMs, subscription agreements or operating agreements.

Syndication terms and legal documents should be reviewed by qualified legal and tax professionals.

Which asset types support syndication modeling?

The detailed multifamily and self-storage underwriting workflows. Both run the same waterfall — equity structure, preferred return, promote and sponsor fees — and both carry the syndication section in their reports.

Single-family and new-construction analyses do not include syndication modeling.

Which plans include syndication modeling?

Syndication modeling is a Gold and Diamond feature, as is side-by-side scenario comparison; the deal report and PDF are included on every plan, and Silver includes 3 scenarios per deal, Gold 10, Diamond unlimited. Team collaboration is a Diamond feature.

Current plan details live on the pricing page.

Model the deal — and how its returns are shared

Underwrite the property, define the structure, and hand your partners a report that shows the waterfall, the preferred return and the LP/GP economics — from one platform.

No long-term contract · Cancel anytime