Self-storage investing: underwrite the business, not just the building
A storage facility is operated more like a business than leased like a building: hundreds of month-to-month units, posted street rates, and a gap between rented and collected that decides the deal. How to analyze one honestly.
For investors evaluating their first facility and for owners of other asset types deciding whether storage belongs in the portfolio.
Self-storage underwriting is the process of building a facility’s income from its unit mix and rates, discounting it to what is actually collected, and carrying the result through expenses, debt and an exit to a return. The asset is judged like any income property — NOI, cap rate, DSCR — but the income is assembled differently: from rentable square feet and rate per square foot across dozens of unit types, on month-to-month terms that reprice continuously.
That month-to-month structure is both the appeal and the risk. Rates can move with demand far faster than an apartment lease cycle allows — and so can a competitor’s three miles away.
Income is built from the unit mix
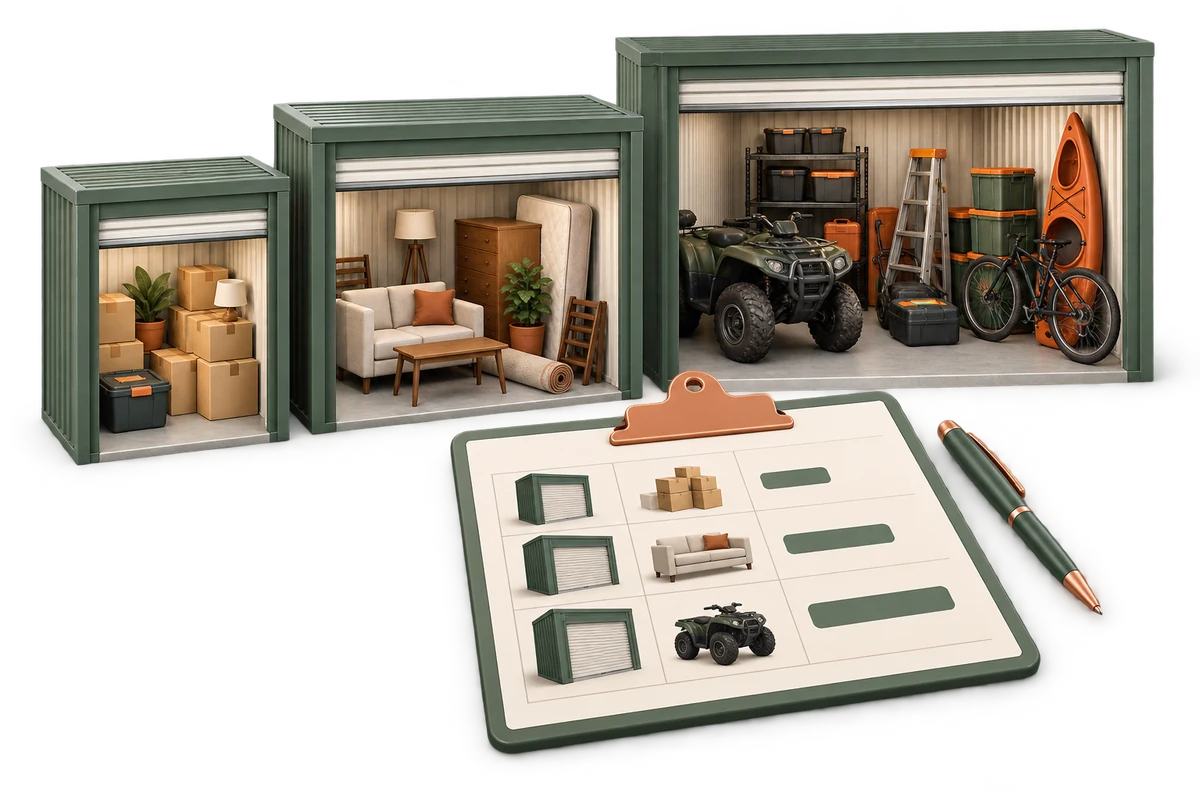
Gross potential income is each unit size times its street rate, summed across the mix — a facility heavy in climate-controlled 10×10s and one heavy in 5×5s are different businesses at the same square footage. Two rate numbers matter: the street rate a new tenant is quoted, and the achieved rate existing tenants actually pay after move-in discounts, web pricing and long-tenured tenants sitting below today’s posted price.
Underwrite on achieved; the distance to street is your upside, priced separately.
Go deeper: Expert Insights: How to Analyze Self-Storage Investments
Physical vs economic occupancy
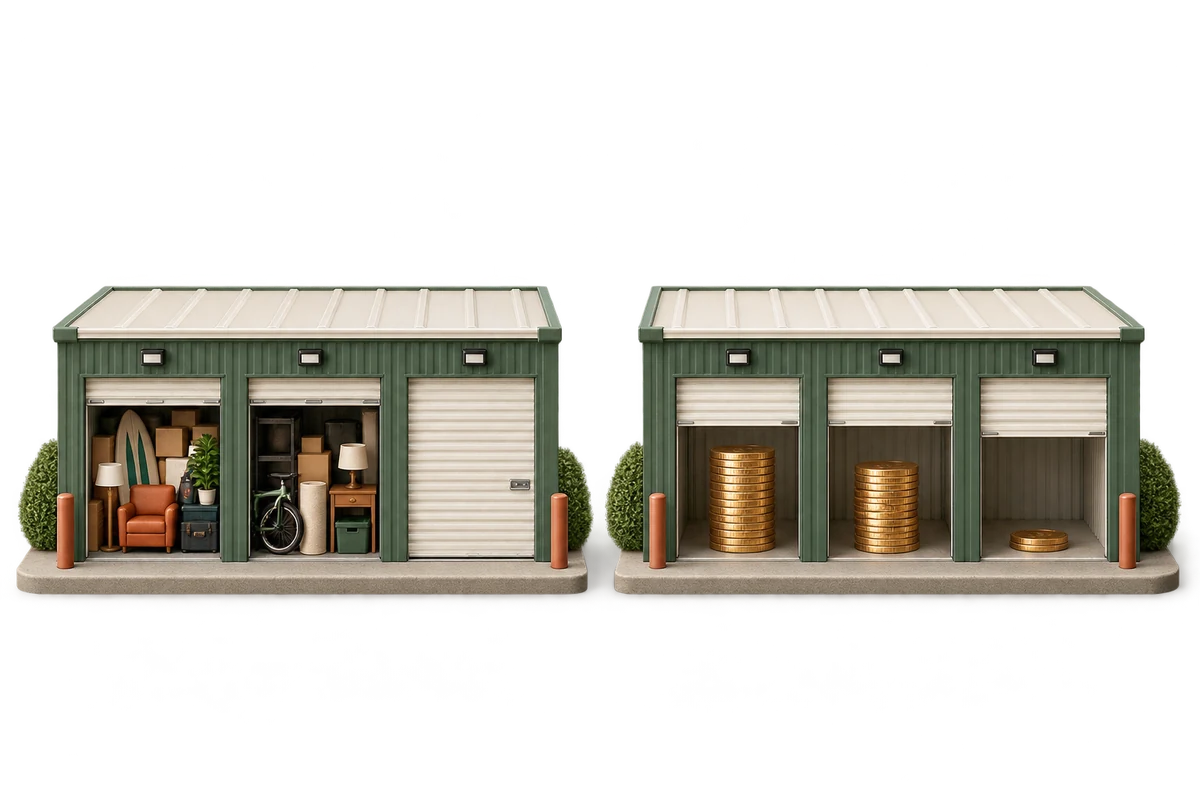
Physical occupancy counts rented doors; economic occupancy counts collected rent against gross potential. A facility can be 92% full and 78% economic once concessions, delinquency and below-street tenants are netted out, and the debt is paid from the economic number.
The gap between the two is usually where the value-add case lives — and where an optimistic pro forma hides.
Other income, expenses and the ratio
Tenant insurance or protection plans, admin fees, late fees and retail sales are real income lines worth modeling explicitly, because they scale with occupancy and management quality. On the expense side — payroll or remote management, property taxes, insurance, marketing, utilities, software — the expense ratio against effective gross income is the cross-check, and a statement that looks lean is often a facility run by an owner who paid themselves nothing.
Go deeper: Real Estate Analysis Software: How to Cash Flow Analysis for Self-Storage
Valuation and revenue per square foot
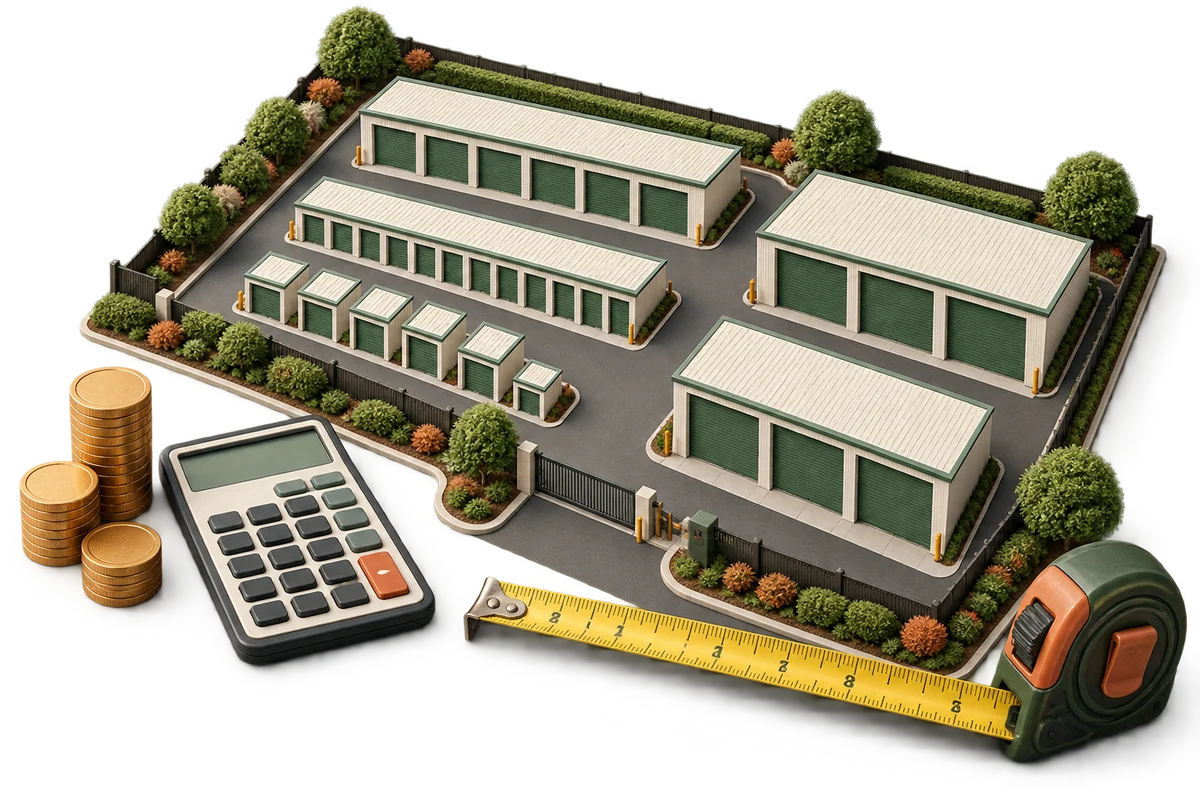
Storage is valued on income: NOI over a cap rate, like any commercial asset. Revenue per net rentable square foot is the metric that makes facilities of different sizes and mixes comparable — computed on both gross potential and collected income, because the difference tells you whether a weak number means weak rates or weak collections, which are different problems with different fixes.
Value-add and expansion
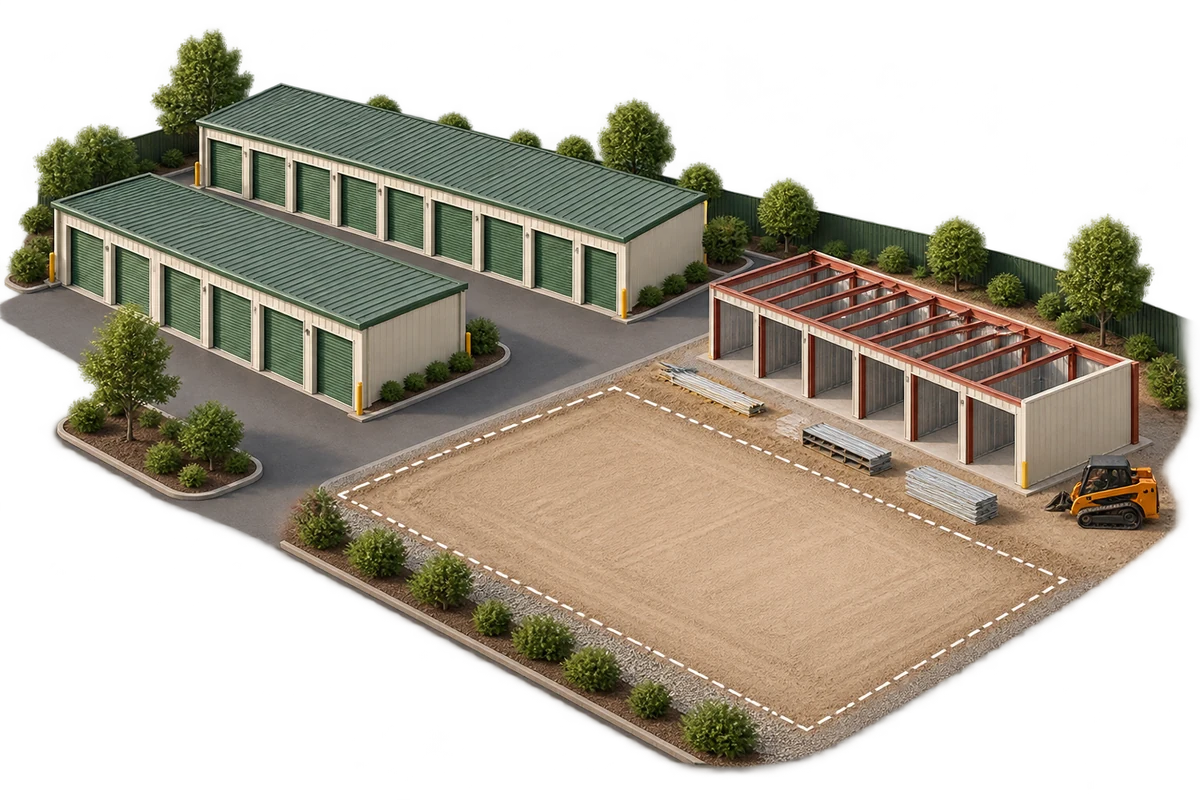
The classic storage value-add levers are pricing discipline (closing the achieved-to-street gap on a schedule), adding income lines the previous owner never ran, cutting expenses with better management, and — where land and demand allow — expansion of the facility itself. Each is an explicit scenario with a cost and a timeline, and the honest model prices the ramp, not just the destination.
Go deeper: Why Self-Storage Should Be Part of Your Investment Portfolio?
Storage vocabulary, briefly
Short versions here; where a full article exists, it owns the detailed treatment.
Unit mix
The facility’s inventory by unit size and type. Income is built from it, unit size by unit size — not from one blended rent.
Street rate
The rate quoted to a new tenant today. The market’s current price for each unit size, and the ceiling your achieved rates are measured against.
Achieved rate
What existing tenants actually pay, net of discounts and tenure. The number to underwrite on; the gap to street is upside, priced separately.
Physical occupancy
Rented units as a share of total units. The flyer number — necessary, and not sufficient.
Economic occupancy
Collected rent as a share of gross potential rent. The number that services the debt, and usually several points below physical.
Revenue per square foot
Annual income over net rentable square feet. The comparability metric across facilities of different sizes and mixes.
Expense ratio
Operating expenses over effective gross income. The fastest test of whether a seller’s statement reflects a professionally run facility.
Go deeper, by subtopic
Analyzing a facility2 articles
The investment case1 article
Related guides: Real Estate Underwriting · Multifamily Investing · Property Research · All guides
 Put it into practice
How DealWorthIt fits in
Model the facility from its unit mix, with assumptions that reflect how storage earns revenue.
- 01
Build income by unit size
Enter unit counts and rates, apply economic occupancy, and add other income.
- 02
Follow the cash flow
Carry operating expenses, financing, and exit assumptions through the storage model.
- 03
Test the opportunity
Save a pricing or lease-up scenario alongside your starting assumptions.
Saved scenario allowances depend on your plan. Side-by-side comparison requires Gold or Diamond.
DealWorthItSample workspaceSelf-storage analysis
| Unit size | Unit count | Street rent |
|---|---|---|
| 5 × 10 | 100 units | $70 / mo |
| 10 × 10 | 120 units | $110 / mo |
| 10 × 20 | 80 units | $180 / mo |
300 units · 90% economic occupancy · $373,680 annual income
Simplified annual example. 75% LTV, 6.5% interest, 30-year amortization. Closing costs, reserves, capital expenditures, and income taxes excluded. Projections are not guaranteed.
Analyze a facility from the unit mix up
Build the revenue from the mix, keep economic occupancy honest, and compare the scenarios that matter.